Lesson 14 of 29
Track withholding tax and foreign tax credits
What you will be able to do
This lesson is for the tax manager. You will open the Withholding Tax tracker, read what it holds for a year, and ask the AI assistant to find foreign tax that was withheld from the entity's income abroad, which can be credited against its corporate tax.
Before you start
- You are signed in with the Tax manager role for Meridian Souq Trading LLC.
- The year's transactions are classified and approved (lesson 6). One of them is interest of AED 45,000 on a deposit in London, from which United Kingdom tax of AED 9,000 was withheld.
- Withholding tax, or WHT, is tax taken off a payment at source. The United Arab Emirates applies a rate of 0 percent to payments abroad, but those payments are still disclosed each year.
Steps
- 1
Open Tax Intelligence, select Returns, then Withholding Tax
In the left menu choose Tax Intelligence. Select Returns, then the Withholding Tax tab. The tab explains what is tracked and has one button, Open WHT Tracker.
- Select Returns
- Select Withholding Tax (WHT)
- 2
Select Open WHT Tracker
Select Open WHT Tracker. The tracker opens on the current year, with four tiles: total transactions, gross foreign payments, WHT withheld and payment types.
- Select Open WHT Tracker
- 3
Choose the fiscal year
Open Fiscal Year at the top right and choose 2025, the year being prepared.
- Select 2026
- Choose 2025
- 4
Read the rule in the blue box
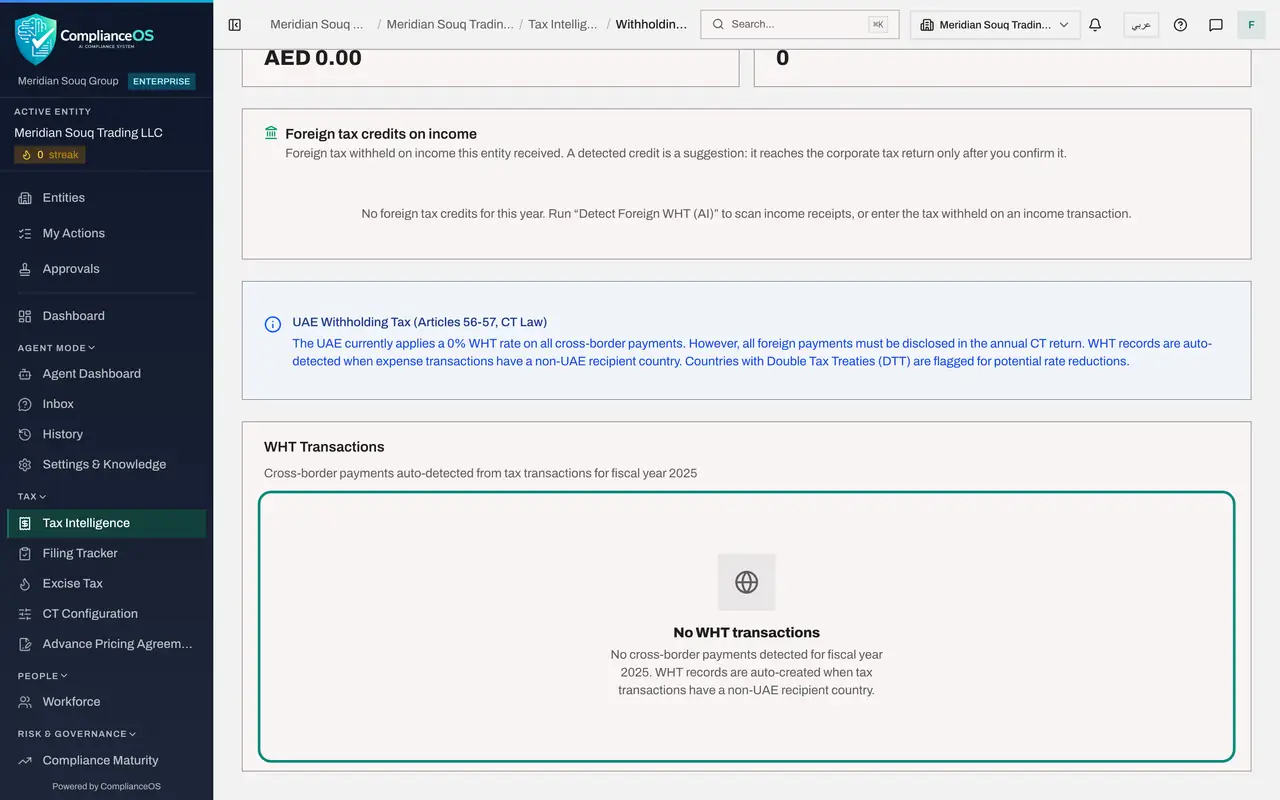
The blue box states the rule. The Emirates applies a withholding rate of 0 percent to payments abroad, but every foreign payment must be disclosed in the annual corporate tax return. Countries that have a double tax treaty with the Emirates, shown as DTT, are flagged because a treaty can lower the tax withheld abroad.
- 5
Read WHT Transactions
WHT Transactions lists payments made to recipients outside the Emirates. A record is created by itself when an expense carries a recipient country that is not the Emirates, which happens for supplier bills and for entries synced from an accounting system. None of the 2025 expenses is a payment abroad, so the list says No WHT transactions. Selecting a row, when there is one, opens its detail.
- 6
Select Detect Foreign WHT
Tax withheld abroad from the entity's own income is found differently. Select Detect Foreign WHT, AI, at the top. The AI assistant reads the year's income and looks for amounts that arrived with foreign tax already taken off. A message reports how many new suggestions it made; here it says zero, because this credit had already been found on an earlier run and is still waiting for a decision.
- Select Detect Foreign WHT (AI)
- 7
Read Foreign tax credits on income
A section appears: Foreign tax credits on income, marked as awaiting your decision. Each detection is only a suggestion; it reaches the corporate tax return only after you confirm it. The line shows the date, the income received, Thamesbridge Bank in London with interest of 45,000 dirhams, the foreign tax withheld of 9,000 with the AI's confidence, the country and the credit limit of 4,050. The limit is 9 percent of the income, the corporate tax the Emirates would charge on it.
- 8
Select Review and confirm
Select Review and confirm on the line. The window Confirm foreign tax credit opens with the income and the credit limit, and four boxes filled from the detection: the foreign tax withheld, the country that withheld it, the withholding rate and the certificate reference. Correct any figure that differs from the bank's tax certificate.
- 9
Confirm the credit
In Withholding certificate reference type the reference printed on the bank's certificate, so the credit can be traced in an audit. Then select Confirm credit. The message says the credit is confirmed and that the corporate tax return applies it the next time it is computed. The line now offers Edit and Reject instead of Review and confirm, and a summary appears underneath: Inbound Foreign WHT, one transaction from the United Kingdom, a treaty country, with foreign income of 45,000 and creditable tax of 9,000.
- Type Withholding certificate reference:
TBB-WHT-2025-0118 - Select Confirm credit
- Type Withholding certificate reference:
How to check it worked
For fiscal year 2025, Foreign tax credits on income lists the Thamesbridge Bank interest of AED 45,000 with foreign tax of AED 9,000 and a credit limit of AED 4,050, confirmed.
Common mistakes
- Confirming every detection without checking the paperwork. The AI assistant reads the wording of each transaction. Check each amount against the bank advice or tax certificate, because a confirmed credit reduces the tax payable on the return.
- Expecting payments abroad that came in by file import to appear under WHT Transactions. That list fills from transactions that carry the recipient's country, such as supplier bills and synced accounting entries. The country column of the import file is not carried into it in this version.
- Looking at the wrong year. The tracker opens on the current year; choose the year you are preparing in Fiscal Year.
Check your understanding
1. United Kingdom tax of AED 9,000 was withheld from interest of AED 45,000. How does that help the entity?
- A.It is refunded by the FTA
- B.It can be credited against the corporate tax due on that income, up to the amount of that corporate tax
- C.It increases taxable income
- D.It has no effect
Show answer
Answer: B. It can be credited against the corporate tax due on that income, up to the amount of that corporate tax
This is the foreign tax credit. The credit cannot exceed the corporate tax the Emirates would charge on the same income.
2. What rate of withholding tax does the United Arab Emirates currently apply to payments abroad?
- A.0 percent
- B.5 percent
- C.9 percent
- D.15 percent
Show answer
Answer: A. 0 percent
The rate is 0 percent, but the payments must still be disclosed with the annual corporate tax return.